Quick answer
Paying cash for equipment avoids finance costs but drains working capital. An equipment loan spreads the cost while you own the asset; a finance lease spreads it while the financier owns it until the end; rental suits short-term or fast-changing needs. The best choice depends on cash flow, how long the equipment will earn, your tax position and whether you want to own it.
Key points
- Cash keeps costs down but drains working capital
- Equipment loans spread cost while you own the asset
- Leases and rentals suit changing or short-term needs
- Ask your accountant about tax treatment before deciding
Start with what the equipment does
Before deciding how to pay, be clear about why you are buying. Will the equipment let you take on new work, finish jobs faster, reduce labour, cut maintenance on old gear or meet a compliance requirement? Estimate what it will earn or save each month. That number decides whether the purchase makes sense at all, and it shapes which payment method is sensible.
Option one: pay cash
Paying cash means no finance costs and no repayments. It is the cheapest option on paper. The hidden cost is working capital. A business that spends a large chunk of its bank balance on a machine may find itself short when wages, suppliers or BAS fall due, and then borrow in a hurry on worse terms. Pay cash only if the business keeps a comfortable buffer afterwards.
Option two: an equipment loan
With an equipment loan, you own the equipment from day one and the lender takes security over it, usually registered on the Personal Property Securities Register. Repayments are spread over a term matched to the equipment’s working life. Because the lender can rely on a saleable asset, equipment loans are often available to newer businesses and owners with imperfect credit. See equipment finance.
Option three: a finance lease
Under a finance lease, the financier owns the equipment and you lease it for a set term, often with a residual payment at the end that lets you take ownership. Leases can suit businesses that want predictable payments and flexibility at the end of the term. The tax treatment differs from a loan, so ask your accountant.
Option four: rent or hire
Renting or operating leases suit equipment you need for a short period, equipment that becomes outdated quickly, or situations where maintenance is included. You never own the equipment, and long-term rental can cost more than buying, but flexibility has value.
Questions to ask your accountant
How will each option be treated for tax? Does the business qualify for simplified depreciation rules for small businesses, and what thresholds apply this year? How does GST on the purchase affect cash flow? Would a lease or a loan suit your tax position better? These questions can change the answer, and business.gov.au also has a useful comparison of leasing and buying.
New or used?
Used equipment can be excellent value, but lenders look more carefully at age, condition and resale value. Dealer invoices and service history help. For private sales, check the PPSR to confirm there is no existing finance owing on the item. Very old or highly specialised equipment may need a larger deposit or other security.
When equipment finance is not enough
If a lender wants a deposit you do not have, or if the purchase is a mix of equipment, installation and fit-out, property security can fund the lot. Property-secured loans run starting at $20,000 and reaching $5,000,000, and no pre-approval valuation is required. Interest may be paid upfront or added on, so the business carries nothing extra each month while the new equipment ramps up.
Run the payback numbers
Divide the cost by the monthly earnings or savings to estimate how many months the equipment takes to pay for itself. Compare that with the finance term. If the equipment pays for itself well inside the term, the repayments are covered by what the equipment earns. Use the repayment calculator with the total cost of any finance offer.
An illustrative example
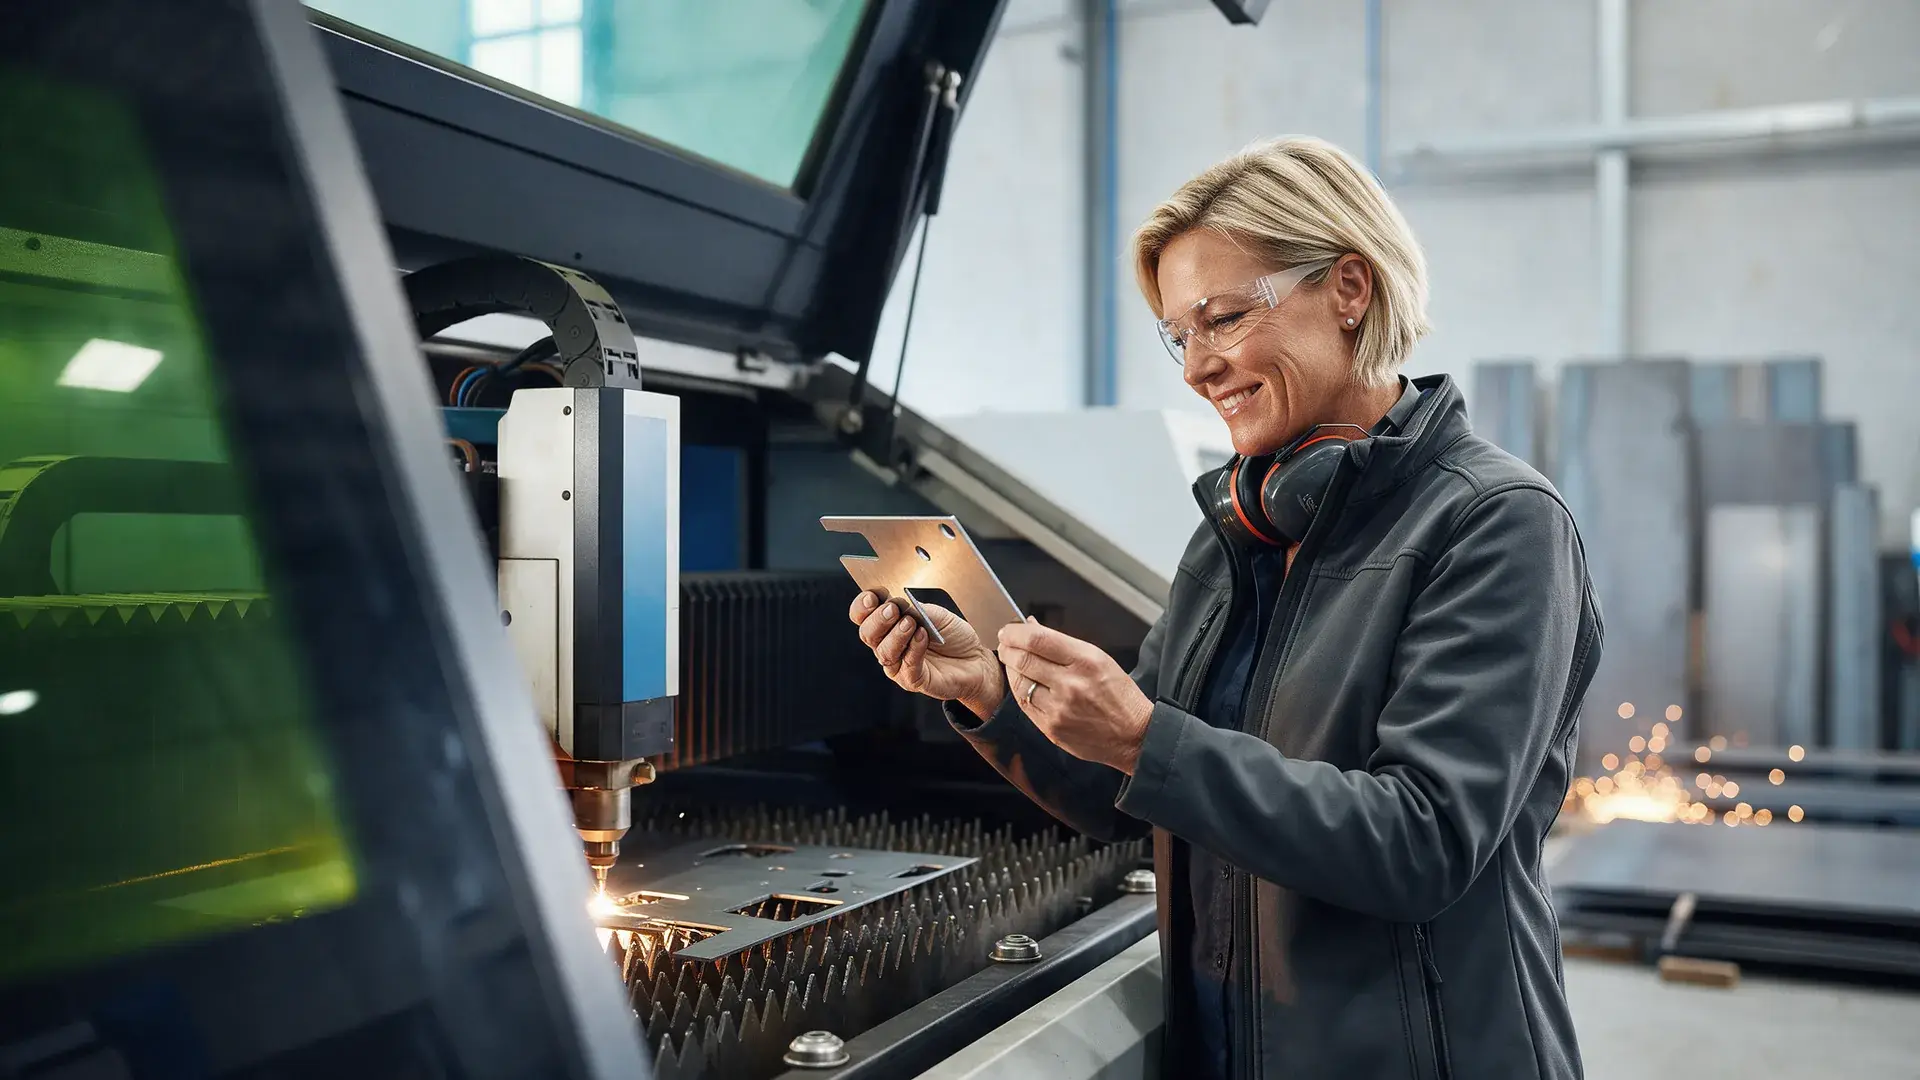
A metal fabricator needed a second laser cutter to meet a new contract. Paying cash would have used most of the bank balance. Equipment finance spread the cost over a term matched to the machine’s life, and the contract income covered the repayments from the first month while the business kept its buffer for wages and steel.
Get equipment options
Make a quick enquiry with the equipment, price and whether it is new or used. We do no credit check to talk, a person checks it, and nothing is passed on. Find the right way to buy.
Frequently asked questions
Is it better to buy equipment outright?
Only if paying cash leaves enough working capital for wages, stock and tax. Many profitable businesses run short of cash after big equipment purchases.
Can I claim equipment as a tax deduction?
Equipment is generally depreciated, and some small businesses can use simplified depreciation rules. Your accountant can advise on what applies.
Can I finance second-hand equipment?
Often, yes, subject to its age, condition and resale value.
What deposit will I need?
It depends on the lender, the equipment and your business. Newer businesses and used equipment often need a deposit.
Should equipment go on a line of credit?
Usually not. Long-life assets are better matched with equipment finance or a term loan.
Prefer to start now? Enquire here
About 60 seconds. No credit check when you first enquire, and a person who handles unusual deals calls you back.