Quick answer
Bendigo businesses declined by banks can access alternative loans that weigh bank statements, purpose and property security. Unsecured funding typically runs from $5,000 to $500,000, and loans secured by Victorian property run between $20k and $5m. Health, education, food, agriculture, tourism and trades businesses across central Victoria are common borrowers.
Key points
- Health and education are major regional employers
- Food, wine and agriculture surround the city
- Heritage tourism and events add seasonal trade
- Victorian property can secure loans with no valuation first
A regional hub with depth
Bendigo is a major centre for health care, education and regional services, with a strong food and wine scene and heritage tourism built on its goldfields history. Surrounding districts support agriculture, viticulture and food processing, while construction and trades serve a steadily growing population.
Common situations in Bendigo
| Situation | Typical route |
|---|---|
| Allied health practice expanding | Equipment finance or unsecured loan |
| Winery funding vintage | Property-secured or seasonal facility |
| Food processor supplying retailers | Working capital or invoice finance |
| Builder or trade with progress gaps | Line of credit |
| Owner with ATO debt and Victorian property | Second mortgage |
Property as security
Residential, commercial and in many cases rural property can secure business loans starting at $20,000 and reaching $5,000,000, and no pre-approval valuation is required. Interest may be paid upfront or added on.
An illustrative example
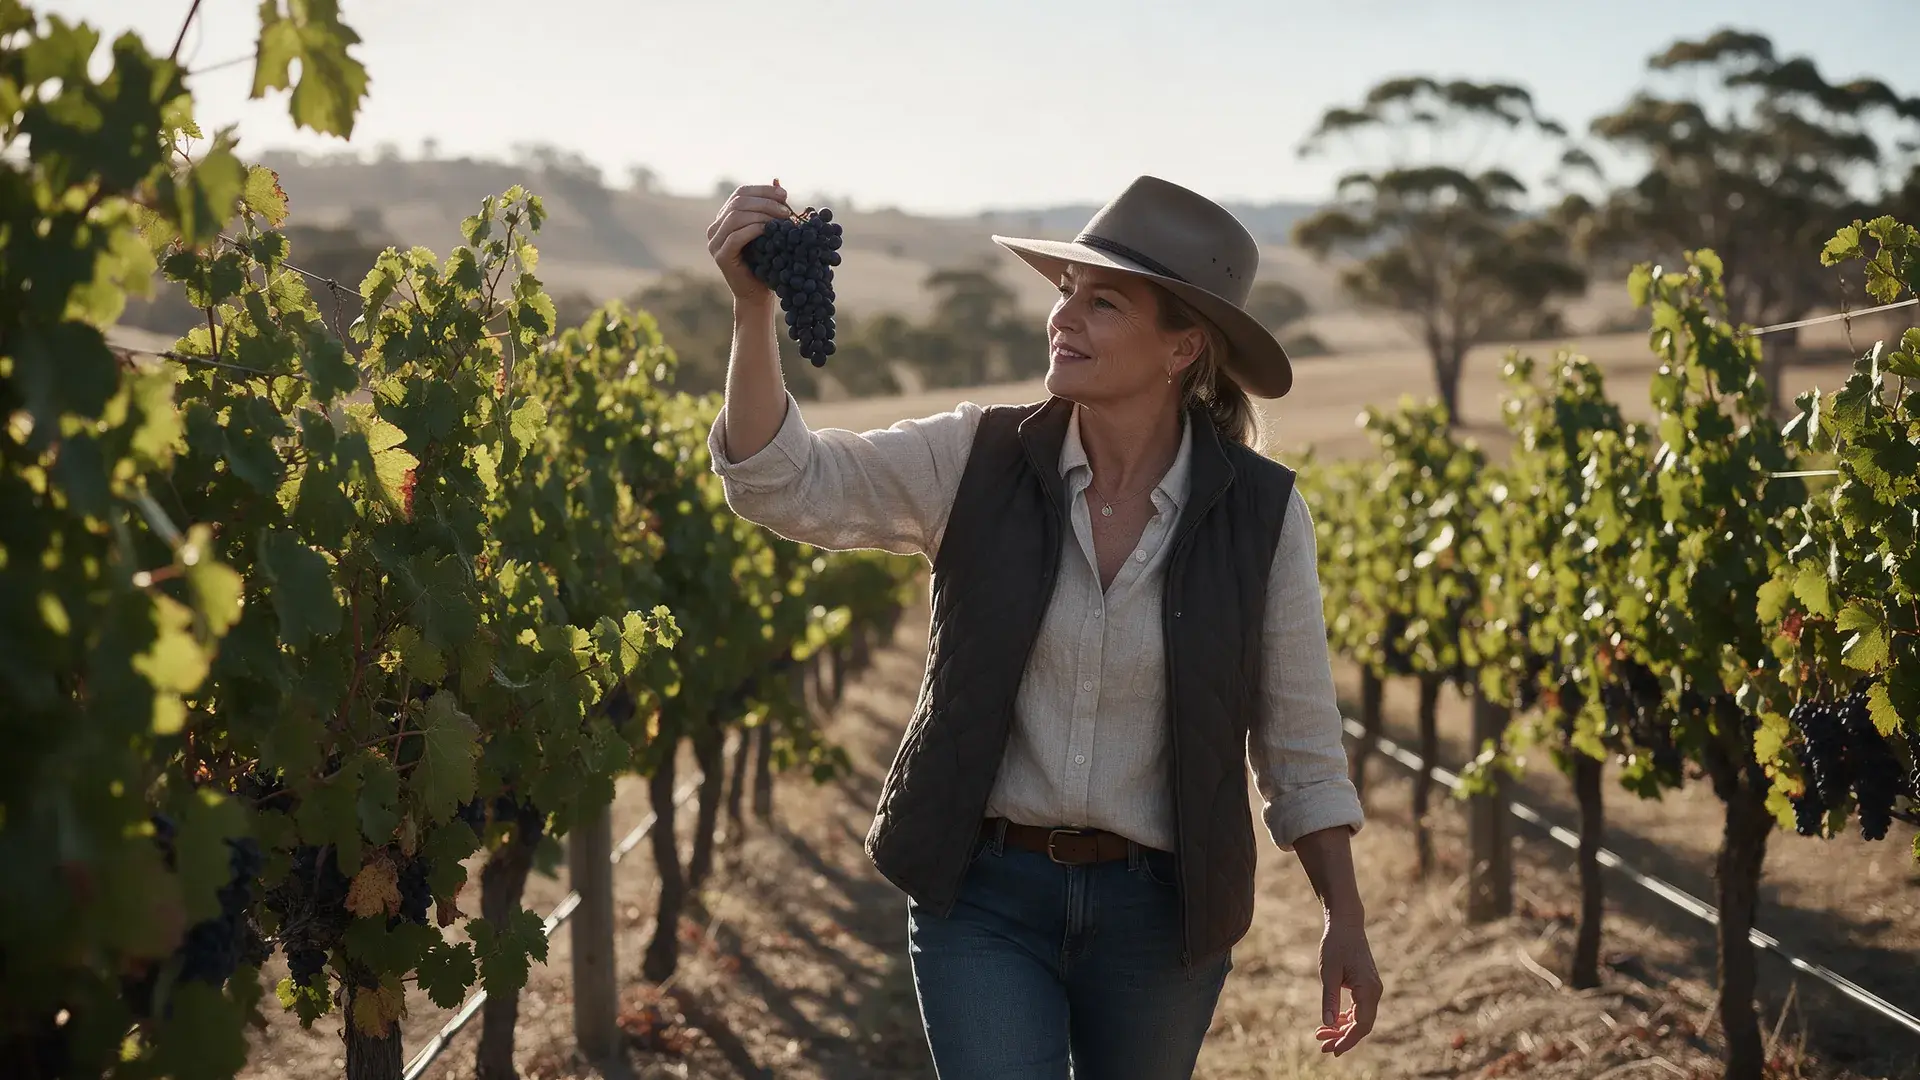
A boutique winery near Bendigo wanted to bottle a larger vintage and upgrade its cellar door. A second mortgage over the owners’ home funded both, with interest added to the balance until the new release was selling.
Nearby
See also Ballarat and Melbourne.
Local industries and their cash flow rhythms
- Health and aged care providers have steady income but large upfront costs for equipment, fit-outs and staff.
- Wineries and food producers in the Heathcote and Macedon Ranges districts work to a vintage and harvest calendar.
- Agribusinesses across the Loddon and Campaspe areas carry seasonal input costs well before sale.
- Heritage tourism and events bring peaks around festivals and long weekends.
- Manufacturing and engineering firms supply regional and metropolitan customers on trade terms.
What to prepare from central Victoria
Business bank statements covering at least a full year, recent BAS, identification and a short summary of what the money is for. Agricultural and wine businesses should note when their main income arrives each year. If you are offering rural property as security, include the exact address and access details, because location affects how the property is assessed. Everything can be handled by phone and electronic signing, so there is no need to travel to Melbourne at any point.
Talk to us from Bendigo
Fill in the short form. Enquiries carry no credit check, a real lender reads it, and your data stays with us. See what your Bendigo business can access.
Frequently asked questions
Do you help businesses across central Victoria?
Yes, including Bendigo, Castlemaine, Echuca and surrounding districts.
Can wineries and food producers borrow?
Yes. Seasonal income is assessed across a full year.
Can health practices finance equipment?
Yes, through equipment finance or unsecured loans.
Can I use rural property as security?
In many cases, yes. Location and access affect how it is assessed.
Prefer to start now? Enquire here
About 60 seconds. No credit check when you first enquire, and a person who handles unusual deals calls you back.